
Best Online Banks in Canada 2026
Canada’s online banks are getting more and more popular as we move more of our lives online. With better interest rates, fewer fees, and increasingly sophisticated mobile apps, it’s getting harder to justify paying $15 or $20 a month for a basic chequing account at the “Big 5 Banks.”
Competition in 2026 is heating up even further, with the 2026 federal budget introducing measures aimed at helping challenger banks like EQ and Wealthsimple compete with Canada’s banking giants. For Canadians, that means more choices, better rates, and potentially thousands of dollars in annual savings.
We’ve updated our Best Online Banks in Canada rankings to compare interest rates, fees, promotional offers, mobile apps, and everyday banking features. Here’s how Canada’s best digital banks stack up against each other and the Big Five.
Best Online Canadian Bank Comparison
While reviewing my personal ranking of Canada’s online banks, please keep in mind that everyone’s requirements are different. Personally, I want the best interest rates for my high interest savings accounts and Canadian GICs. I also want to note that we’ve included EQ’s Notice Account separate from the everyday account because the two have quite different characteristics.
 4.8 / 5
3.70%
1.50% + 1.50% Bonus
 4.8 / 5
3.70%
3%
 4.4 / 5
Not Available
2% - 2.75% through Neo HISA
 4.1 / 5
3.60%
0.30%
 4 / 5
3.40%
1.30%, with special promo rate of up to 4.70%
 3.8 / 5
3.55%
0.35% (3.70% teaser rate for 7 months)
 3.4 / 5
3.55%
2.25%
No Available Promotion
 2.9 / 5
3.60%
1.05%
No Available Promotion
 2.4 / 5
4.05%
3%
No Available Promotion
Now, keep in mind that while virtual banks are competing with the big brick and mortar banks, they still vary quite a bit in their offerings. Some of the new online banks in Canada offer teaser rates (which I don’t love) while others have a lower, but consistent rate that hold steady over time.
Similarly, some digital banks are basic and only offer one or two account options while others are growing to add accounts other than chequing and savings including TFSAs and RRSPs and even mortgages.
So if you are looking for the best online bank in Canada when it comes to your personal wishlist, read on to see which boxes our leading competitors check off.
How We Pick Online Banks
For most Canadians, online banking is no longer the alternative – it’s the default. If you’re comparing an online bank to a traditional bank, these are the features that actually matter.
When comparing banks in Canada, we ask:
- Are there monthly account fees?
Many online banks charge $0, while traditional chequing accounts often cost $10 to $20 per month. - What interest rate do I earn on my cash?
This is one of the biggest advantages online banks offer, especially for savings accounts. - Are Interac e-Transfers free?
Most of the best online banks now include unlimited free e-Transfers. - Can I access cash easily?
Check ATM access, withdrawal fees, and whether the bank offers a physical or prepaid card. - Does the bank have a good mobile app?
A clunky app can ruin the whole experience. Mobile cheque deposit, bill payments, and transfers should all be easy. - What everyday banking features are included?
Look for bill payments, direct deposit, recurring transfers, joint accounts, and linked savings options. - Is customer support actually helpful?
Online chat, phone support, and clear service hours matter more than most people realize. - Is my money protected?
Make sure the bank or its partner institution offers CDIC coverage or provincial deposit insurance. - Are there any limitations or tradeoffs?
Some online banks don’t offer cheques, branch access, bank drafts, or full-service lending options. - Will this account actually save me money?
Lower fees and better interest rates can easily put hundreds of dollars a year back in your pocket.
If a bank checks most of the boxes above, it’s probably worth a serious look. And if you’re currently paying monthly fees for a basic chequing account, switching to a strong online bank can be one of the easiest financial upgrades you’ll ever make.
Canadian Banking Comparison Checklist
Before opening a new bank account, check these 8 things:
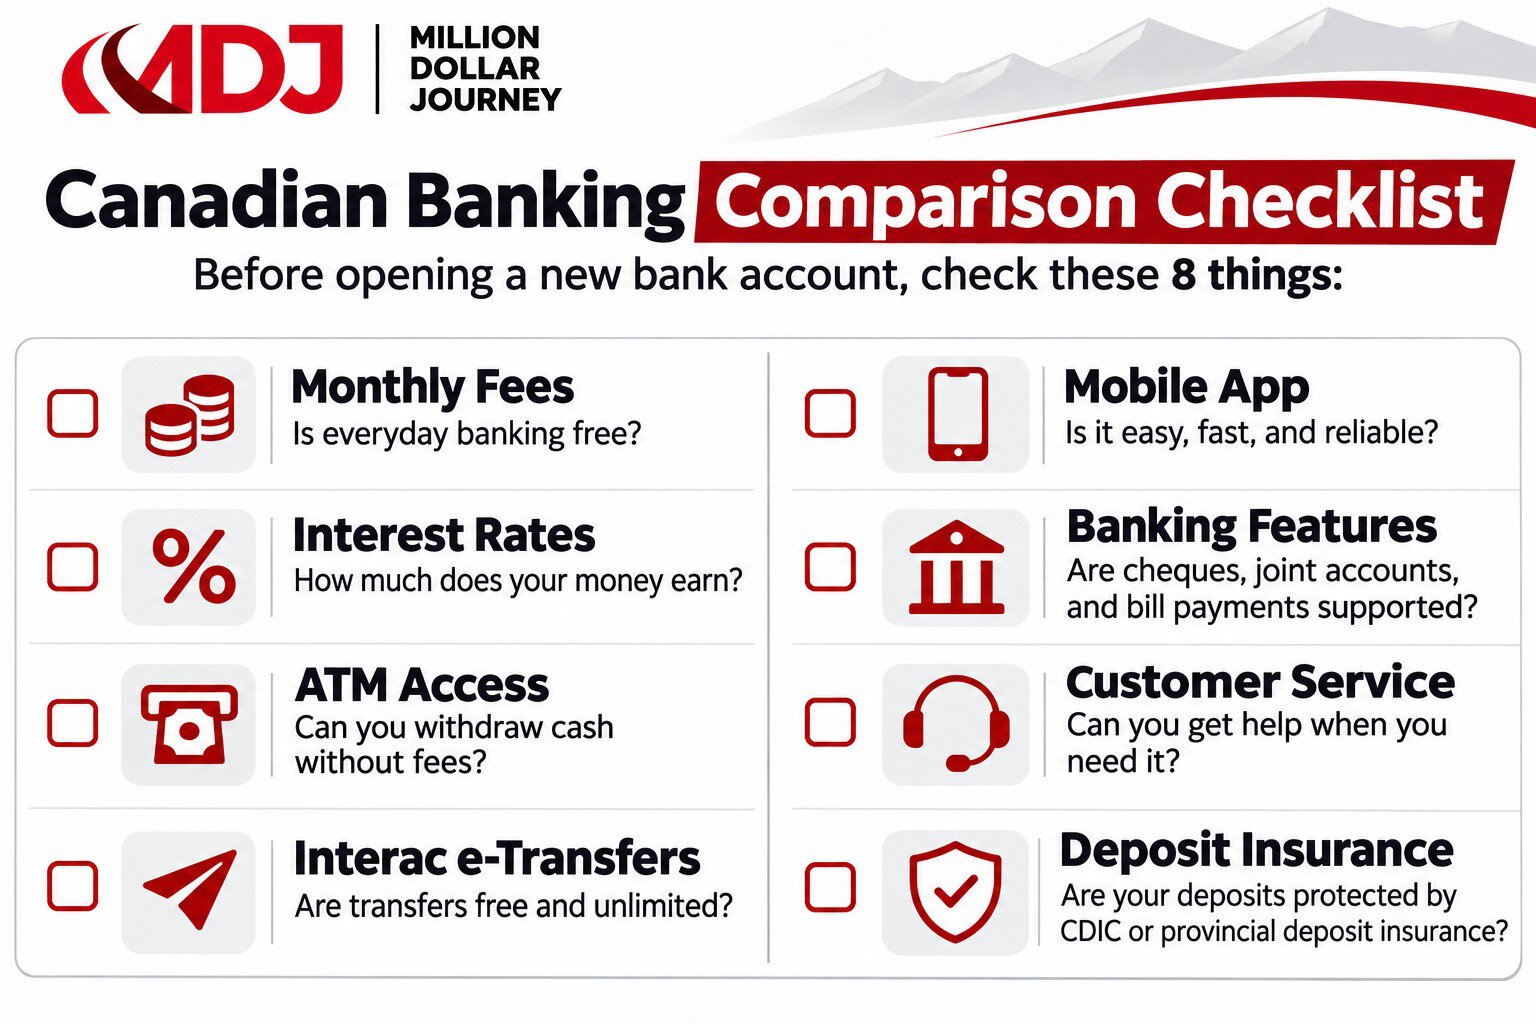
The bottom line: The best bank isn’t necessarily the one offering the biggest promotional bonus. It’s the one that makes everyday banking easy while keeping more money in your pocket.
Online Banking Costs and Fees
Big banks have overhead costs that trickle down to you, the client, which means you have to pay more for your accounts and frequently are offered lower interest rates. In comparison, online banks don’t have those big overhead costs which means they can offer you higher rates and, depending on the online bank, even free bank accounts.
Here’s a case study against that illustrates the long-term savings difference:
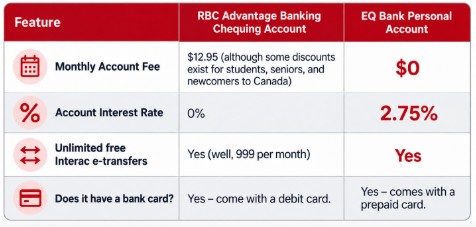
$525 Difference In Only 1 Year! (Keep $10,000 in an RBC chequing account and pay $155 in annual fees, or bank for free with EQ Bank and earn $370 by putting that money into its 3.70% one-year GIC. Same $10,000, very different results.)
What Online Banks Don’t Provide
There are a few areas where online banks are not up to par with brick and mortar banks. They are lacking in personal touch since you likely won’t be communicating face-to-face with an actual person. (Although, if you’re like me and prefer an online chat or brief email exchange to waiting in line at a bank, then you can still get person-to-person help – just in a non-traditional way.)
Depending on the online bank, there may be fewer ATMs available – which could be a downside if you deal with cash frequently. If you regularly utilize ATMs, it would be worth choosing an online bank that has free-to-use ATMs that are conveniently located for you.
Online banks are often lacking in the all-in-one packages that many of the bigger banks can offer and there are sometimes limitations in terms of the types of services offered such as mortgages and investments. You also won’t be getting a safety deposit box with an online bank!
Are Online Banks Safe?
When it comes to the safety of online banks in Canada, the natural question for most of us, is are the digital-only banks as safe as the traditional brick-and-mortar banks like RBC, TD, BMO, etc. The good news? Canadian online banks are just as safe as their conventional counterparts.
There are multiple layers of protection in place to ensure the security of both your money and your personal information at all of the online banks in Canada (as they are Chartered Banks as defined by government regulations).
First, in regards to regulatory oversight these digital banks aren’t some fly-by-night operations. They operate under the supervision of the Office of the Superintendent of Financial Institutions (OSFI), which enforces high standards of financial security, risk management, and operational reliability across all Canadian financial institutions.
Every online bank must meet strict capital and liquidity requirements to prove they can withstand financial challenges. They are required to undergo regular audits and report financial statements, making it impossible for financial trouble to creep up unnoticed. Many of these banks, like EQ Bank and Tangerine (owned by Scotiabank), are backed by well-established financial institutions that publish their financials every quarter, adding yet another layer of transparency.
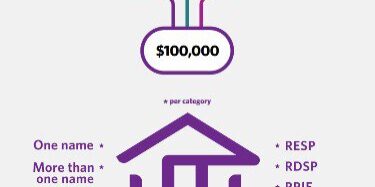
Most of Canada’s best online banks are Canada Deposit Insurance Corporation (CDIC) members. This means that deposits of up to $100,000 per insured account type are 100% protected – even in the highly unlikely event that an online bank were to fail.
That “per account” is interesting too, because that means you could theoretically have a $100,000 TFSA, Non-registered account, RRSP, etc. So could your spouse. So you could be fully insured by the Canadian government for a pretty large amount of money! To put your mind further at ease, Canada hasn’t had a major bank failure in decades. Our banking system is globally recognized as one of the safest in the world.
If you’re worried about online banking security, you should know that digital-first banks actually invest more in cybersecurity than most traditional institutions. Why? Because their entire business model depends on providing secure, seamless online services.
Here’s what they do to keep your money safe:
End-to-End Encryption – Your data is fully encrypted, making it almost impossible for hackers to intercept.
Two-Factor Authentication (2FA) – A second verification step (like an SMS code or authentication app) ensures that even if someone gets your password, they still can’t access your account.
Fraud Monitoring & AI-Based Threat Detection – Online banks continuously scan for unusual activity and can automatically freeze transactions if something looks suspicious.
Security Guarantees – Some banks, like EQ Bank, offer a full reimbursement if unauthorized transactions occur on your account.
So if security is your main concern, you can feel just as safe keeping your money in an online bank as you would at any of the Big Five.
EQ Bank – My Pick For The Best Online Bank Account in Canada
Since 2016, EQ Bank has been dedicated to affordable, convenient digital banking.
EQ Bank offers personal high-interest savings accounts (individual, joint, and USD) as well as competitive GICs, RRSPs, TFSAs and FHSAs. They also offer a “Mortgage Marketplace” where you can compare mortgage products offered by lenders across the country. Check out our full EQ Bank Review for more details.
EQ Bank just keeps getting better. In 2023 they introduced the new EQ Bank Card. The Bank Card is a huge leap forward for customers, as it removed one of the few friction points when it came to everyday uses. The new addition coming this year is a business account, as well as the recently launched EQ Notice Account.
By giving Canadians a convenient way to pay for stuff, using the same crazy high-interest savings account that they earn a ton of interest on, EQ continues to separate themselves from the pack.
And best of all, EQ is now available in Quebec!
Pros:
- Great interest rates on savings accounts and GICs
- No fees
- Excellent mobile app
- Cashback bank card
- Canada’s only Notice Account (super-high interest)
- Excellent small business accounts
Cons:
- No RESP option
Best Feature: No fees, great rates, convenient purchasing power, and a fantastic app.
Neo Financial — Runner Up for Best Online Bank in Canada
Neo Financial, a Canadian fintech company, was founded in 2019 and offers a variety of products. It has taken second place in our list of Best Online Banks in Canada.
Neo Financial offers a hybrid high-interest savings account combining a 2% everyday interest rate along with free transactions and point-of-sale availability of a chequing account. You can read more in my full Neo Savings Account review.
Its cash back Mastercard is the best credit card for the average Canadian. With the premium card you’ll receive an average of 5% cash back at all Neo Partner stores. The card has a unique user-friendly app, and a quick approval process and is available to Canadians with credit scores as low as 600.
Pros:
- High everyday interest rate
- Free e-transfers & bill payments
- No fees or minimum balances
- Best cash back offers of any credit card in Canada
Cons:
- Not available in Quebec
- Limited joint accounts
- No USD accounts
- No GICs
Best Feature: excellent everyday interest rates of 2% – 2.75% and the Neo Financial Mastercard – Canada’s best credit card for cash back offers.
Tangerine — Oldest Canadian Online Bank
Tangerine, a digital-only subsidiary of Scotiabank, was originally ING Direct, a pioneer in branchless banking in the 1990s. Acquired by Scotiabank in 2012, Tangerine was considered Canada’s top online bank for years.
Tangerine offers no-fee chequing and savings accounts, no-fee cashback credit cards, mortgages, and investment account options. Currently, they are offering some of the highest GIC rates in Canada. You can read more in my full Tangerine review.
Currently, when you open a new account with Tangerine you can get an interest rate of 4.5% in their high interest savings account, which is great. However, after 5 months that drops to a measly 0.30% which is certainly nothing to write home about.
Pros:
- Very competitive GIC rates
- Excellent online platform and app
- Solid no-fee credit card options
- Good promotional offer
- Best all-in-one online bank
Cons:
- Everyday interest rate is only 0.30%
- Investment account options can’t beat the best online brokers.
Best Feature: The No-Fee Money Back Credit Card and the convenience of a one-stop bank.
Scotiabank — Best Big Bank for Online Banking
The only one of Canada’s big banks to make our list, Scotiabank was founded in 1831. It offers a variety of banking packages, most of which you can apply for and access completely online.
Scotiabank offers chequing and savings accounts, a line of credit cards, and investment accounts. Their Ultimate Package includes a huge number of features, from a safety deposit box to cheques and bank drafts for no extra fee. With this account you can benefit from the best of both online and brick-and-mortar services.
Scotiabank is currently offering new clients a $1,000 welcome bonus if they sign up for their Preferred or Ultimate Packages and set up two automatic payments or deposits. You can read all the details in our Scotiabank Review.
Pros:
- Excellent perks and inclusions
- Generous welcome bonus
- Premium credit card fee waived
Cons:
- Hefty fee unless you maintain a minimum balance
Package is only worth it if you actually want all the bells and whistles
Best Feature: The package inclusions. Big banks are pricey, but Scotiabank’s packages offer good value for that money.
Simplii Financial – Best Online Bank Welcome Bonus
Simplii Financial falls under the CIBC umbrella and was known as PC Financial until 2017.
Simplii offers the full range of online banking features: chequing and savings accounts, credit cards, mortgages, loans, and investment options including GICs, RRSPs, TFSAs, and mutual funds. Learn more about Simplii Financial here.
Simplii is currently offering a welcome bonus of $350 if you open a chequing account. While that’s the same amount as Scotiabank offers, there are fewer requirements to qualify. New savings accounts also receive 5 months of a 5% promotional interest rate.
Pros:
- Excellent welcome bonus
- Variety of banking options
- Low fees
Cons:
- Low everyday interest rate for savings accounts
- GIC rates aren’t competitive
- Customer service isn’t great
- Platform isn’t user friendly
Best Feature: That sweet welcome bonus and the variety of offerings.
Motive Financial – Earn Interest on Online Chequing Account Balance
Motive Financial is one of the biggest online banks in Canada and is a division of the Canadian Western Bank.
Motive Financial offers a chequing account and a savings account, plus GICs, TFSAs, and RRSPs. New clients opening a Motive Savvy Savings Account will see an interest rate of 2.25% – a really good rate compared to many other online banks. While there is no monthly fee for this account, the other fees really add up and make their high interest rate less attractive.
Motive Financial lets you earn interest on your chequing account too. The Cha-Ching Chequing account will bring you 0.15% in interest. It has free Interac e-transfers, unlimited free transactions, no monthly fee, and 50 personalized cheques are included. Check out my Motive Financial Review for full details.
Pros:
- Chequing account earns interest
- Savings account has a great interest rate
- No monthly fees
Cons:
- Additional fees can add up
- Limited transactions for savings accounts
Best Feature: Earning more than 0.01% interest on a chequing account.
Alterna Bank – Online Bank With a Qtrade Welcome Bonus
Alterna Bank is part of the Alterna Savings Credit Union, which is based in Ontario. They offer everyday banking accounts, mortgages, and investing options. Their HISA interest rate is higher than some of the others on this list, at 1.05%, but what really makes Alterna Bank stand out is their partnership with Qtrade.
While Motusbank has also partnered with Qtrade, Alterna is offering new investors up to 5% cashback if they open an account and invest $5,000 with Qtrade Direct Investing. Check out our Qtrade Review to see why they’re MDJ’s top recommended online broker in Canada.
Pros:
- Competitive interest rate
- Qtrade welcome bonus
Cons:
- Minimum investment of $5,000 to be eligible for the Qtrade bonus
Best Feature: A Qtrade partnership that gives you cashback.
Oaken Financial – Available in Quebec
Oaken Financial’s parent company is Home Trust, Canada’s largest independent trust company. It only has one savings account and some GIC options. However, what it lacks in product offerings it makes up for in value, with a standard interest rate of 3.4%.
The other thing that makes Oaken Financial a standout is that Quebec residents are able to open an account with them which is not the case for many other online banks in Canada.
Pros:
- Excellent interest rate on savings account
- Available to Quebec residents
- No fees
- Business accounts available
Cons:
- Only a few offerings
Best Feature: The excellent standard interest rate and the availability in Quebec.
Types of Online Bank Accounts
Unlike traditional banks, each online bank offers something a bit different. As you may have noticed from my mini-reviews, not every bank will offer all of the types of bank accounts listed below. For now, here are the main types of online bank accounts available in Canada.
- Savings Accounts that you can park your money in and earn a bit of interest at the same time.
- Chequing Accounts that allow for easy access to your money for monthly bills and daily expenses.
- High Interest Savings Accounts offer a higher interest rate than regular savings accounts. Online banks are known for having the highest interest rates in Canada.
- TFSA Accounts are Canadian government sponsored accounts that allow you to invest up to a certain amount and then save, grow, and withdraw your money tax free.
- Hybrid Savings and Chequing Accounts act like a savings account in terms of earning interest, but lets you spend like a chequing account.
- Investment Accounts allow you to easily invest your savings to help you plan for the future.
- Student Accounts work the same as regular chequing and savings accounts, and are a great way to help younger people become more financially savvy.
- Joint Accounts are a good option for a situation where more than one person needs to be able to manage funds, send money, pay bills, make withdrawals, etc.
- Senior Accounts offer more discounts and freebies to help those in retirement save more money.
Best Online Bank Mobile App
There’s no denying that Canada’s Big Banks – RBC, TD, BMO, Scotia, and CIBC – have put together some pretty polished banking mobile apps over the years. But when it comes to overall user experience, I’d happily stack EQ Bank’s app up against any of them.
You can immediately tell that EQ was built as a digital-first bank. This isn’t a legacy system that’s been dragged online with some duct tape and a redesign – it’s a mobile experience that’s been crafted from the ground up for Canadians who bank from their phone.
The interface is clean, intuitive, and straightforward. Whether you’re moving money between accounts, exchanging currency, sending an eTransfer (free, of course), or locking in a GIC inside your TFSA or RRSP, it all happens in a couple of taps.
Now, I’ll be the first to admit that I still do most of my banking on desktop – I’m in front of a computer all day anyway – but I know plenty of folks who use EQ exclusively through the app and love it.
The only real critique I’ve seen (mostly on the Canadian personal finance subreddit) is that biometric login could use some fine-tuning. I still use a good old-fashioned password, so I can’t speak to that personally – but it seems like a small nitpick in exchange for everything the app offers, especially when you factor in the zero monthly fees and elite interest rates.
Online Banking in Canada: FAQ
Canadian Virtual Banks in 2026 – No Fees and the Right Fit
Paying $15 or $20 a month for a basic bank account is getting pretty tough to justify these days. Canada’s best online banks now offer nearly everything most people need, often with no monthly fees, better interest rates, and convenient mobile apps.
For my money, EQ Bank remains Canada’s best overall online bank in 2026. Between its no-fee everyday banking, competitive savings rates, excellent Bank Card, and innovative Notice Savings Accounts, EQ has consistently found ways to give Canadians more value for their money. What I love most is that they keep adding new features every year without sacrificing their interest rate advantage.
That doesn’t mean it’s perfect. Tangerine and Simplii offer excellent alternatives, while the Big Six still make sense if you regularly need in-person service or more specialized banking products.
Quick Note: Keep an eye for banks that pull a “bait and switch” when it comes to promotional interest rates. I’m always suspicious of companies that lure you in with an artificially-high teaser rate for a few months before quickly ratcheting down the interest you collect forever going forward.
But if you’re still paying monthly banking fees just because “that’s where I’ve always kept my money,” then it might be time to ask yourself what exactly you’re paying for.

EQ Bank’s everyday interest rate is only 1.0% if you don’t have direct deposits with them.
Technically not a bank but you can do most banking functions with Wealthsimple.
I’ve been “banking” with them for a year and it works well.
I like that I was able to consolidate my investing and banking in a single view.
Maybe this article could be updated with fintechs?
Must one be a Canadian resident for all of these? I didn’t catch that topic in my fast read. Thanks, Kyle
Yes, I believe so Erick.
Good article but one note I would add is that as far as I can tell, motusbank has the same partnership with QTrade Investor and VirtualWealth as Alterna Bank.
https://www.motusbank.ca/Accounts/Investing