
Best Canadian Dividend Stocks – September 2026
Our top Canadian dividend stocks for 2026 are companies with sustainable dividends, growing earnings, and a long, proven track record of increasing their payouts to shareholders.
Unlike lists that simply rank stocks by dividend yield, we focus primarily on dividend growth consistency, earnings-per-share (EPS) growth, revenue growth, payout sustainability, and valuation. That’s why some lower-yielding companies such as Toromont and Canadian National Railway rank ahead of stocks offering much higher yields.
Fortis is our top Canadian dividend stock for 2026, combining 52 consecutive years of dividend increases with predictable regulated earnings and an attractive dividend yield.
The table below contains our current top 10 picks. We update the underlying financial data regularly and review the rankings throughout the year.
Ticker | Div Streak | Dividend Yield | 5yr EPS Growth | 5yr Dividend Growth | Payout Ratio | P/E | |
Fortis | FTS.TO | 52 | 3.40% | 5.33% | 4.65% | 73.86% | 22.14 |
Toromont Industries | TIH.TO | 36 | 1.11% | 10.45% | 10.35% | 34.05% | 32.46 |
Canadian National Railway | CNR.TO | 29 | 2.18% | 3.10% | 8.30% | 46.78% | 21.53 |
Canadian National Resources | CNQ.TO | 25 | 3.56% | 17.78% | 21.46% | 45.38% | 12.49 |
Emera | EMA.TO | 17 | 4.28% | 11.77% | 2.62% | 85.60% | 21.59 |
National Bank | NA.TO | 16 | 2.51% | 8.02% | 11.89% | 45.77% | 17.62 |
Alimentation Couche-Tard | ATD.TO | 16 | 1.08% | 7.26% | 19.14% | 17.60% | 16.79 |
Brookfield Corp. | BN.TO | 16 | 0.74% | -18.53% | -5.22% | 48.42% | 74.40 |
Waste Connections | WCN.TO | 15 | 0.89% | 13.25% | 10.28% | 31.01% | 38.49 |
?????? (Hidden, click for access) | ???.?? (Hidden, click for access) | ?? | ?.??% | ?.??% | ?.??% | ???.??% | ??.?? |
* Note: Data on this article updates periodically. If you are looking for real time data and guidance, read our recommendation below.
Good to Know:
Don’t only focus on dividend yield. A very high dividend yield can actually be a warning sign! If a stock’s yield is significantly higher than its historical average or sector peers, it could indicate financial trouble, a potential dividend cut, or a falling stock price. Our best high yield stocks in Canada goes into that in more detail.
How we Pick the Top Dividend Stocks
Before getting deeper into my updated 2026 dividend stock picks, I have to revisit my 2025 recommendation: TD Bank. My thesis was that its U.S. money-laundering penalties, while serious, were not going to permanently damage the bank’s core business – and that the market had priced in far too much bad news.
That call worked out even better than expected. TD delivered a total return of more than 50% in 2025, and its shares are up ANOTHER 30% in 2026 (even I didn’t see that one coming). Not bad for what was supposed to be one of Canada’s most troubled blue-chip stocks.
Given the strong earnings picture, and continued inflation moderation, Canadian dividend stocks look very attractive for the long term.
FT
We don’t use a rigid formula to rank dividend stocks. Instead, we look for companies that combine sustainable payouts with long-term earnings and revenue growth, a history of dividend increases, reasonable payout ratios, and attractive valuations. Current dividend yield definitely matters, but you should never sacrifice business quality or dividend sustainability just to get a higher yield.
You’ll see that many of our Canadian dividend picks are in stable industries such as banks, insurers, pipelines, and utilities. I love these companies because they have such high barriers to entry. Good luck creating a pipeline from scratch in Canada these days!
Truthfully, I have no idea what artificial intelligence is going to mean for every company around the world. I think that it’s probable big companies like RBC and CNQ will figure out ways to get 3-5% more efficient using various types of AI to focus on more targeted marketing, getting more production out of fewer employees etc. That said, I don’t know where some of these bolder “10x” predictions are coming from.
Consequently, I think the trends from the second half of 2025 are a good bet to continue into 2026. In the latter half of last year, we saw Canadian blue-chip stocks substantially outperform the Nasdaq tech darlings.
In fairness, the big tech companies in the US have been on an incredible 10-year run, and are great companies – you just have to pay a very, very, high premium to buy a piece of them right now. Canada’s best dividend stocks aren’t valued nearly as high. While it’s possible (maybe even probable) we see a sideways market for the next 5+ years, those 4%+ dividends are likely to just keep rolling right along!
Mike Heroux over at the Dividend Stocks Rock platform confirmed what my instincts were telling me in regards to interest rate movements and current events at his last free webinar. As my go-to source for dividend info, I highly recommend checking out Mike’s Pro services as it makes organizing these dividend watchlists so quick and easy. For a limited time, MDJ readers get a 33% lifetime discount – your price will NEVER go up.
*Free signup with access to stock tips & webinars + 60 days money back guarantee on the pro version.
Up to Date Dividend Stock Data & Picks
The easiest way to keep up to date with the best dividend stock picks, is by signing up with Dividend Stock Rock. DSR is not just a weekly newsletter with stock picks. It’s a program that will help you manage your portfolio and improve results using unique and sophisticated tools.
For my full 32-stock list of Canadian dividend earners, plus 74 U.S. Dividend All-Stars, check out DSR – the platform I personally use for my dividend stock research. The person behind DSR is Mike, the most prominent and active dividend stock blogger in Canada and is a certified financial planner since 2003.
You can first read our detailed DSR review, or sign up now by clicking the button below. Our readers are eligible for an exclusive 33% off discount using code MDJ33.
Best Canadian Dividend Stock To Buy Right Now
I selected Fortis as my 2026 Canadian dividend stock pick due to being generally pessimistic about the state of things. So far that pessimism has paid off. The rush to safety has meant that Fortis shares are up 10.5% so far this year, and when you tack on a 3.31% annual dividend, we’re getting solid returns in a very low-risk investment vehicle. While you could have gotten similar returns in a TSX index fund, you would have had to put up with a lot more up-and-down action!
A “boring” efficiently-managed utility is a great (if unexciting) bet right now due to power demands and the future outlook of data centre construction. Quickly rising interest rates could hurt the stock, but the Bank of Canada is going to get major pushback if they try that right now.
My National Bank pick from three of the last five years continues to perform well, as does TD after working through its U.S. money-laundering problems. But after several excellent years for Canadian bank stocks, bank valuations no longer look nearly as compelling to me.
Consequently, I’m going with the much more defensive Fortis for my 2026 pick. I’m not sure how long the macroeconomic party can last, and this is exactly the sort of environment where a boringly dependable, wide-moat stock can really shine.
Just to give you some idea of how good things went last year for bank stocks, let’s take a look at RBC (at various times the biggest or second biggest stock in Canada over the last ten years). RBC was up 35% in 2025, and it’s up about 167% over the last five years. While its earnings have grown in that stretch, they haven’t grown nearly as vast as the stock price. Resulting in the following P/E chart:
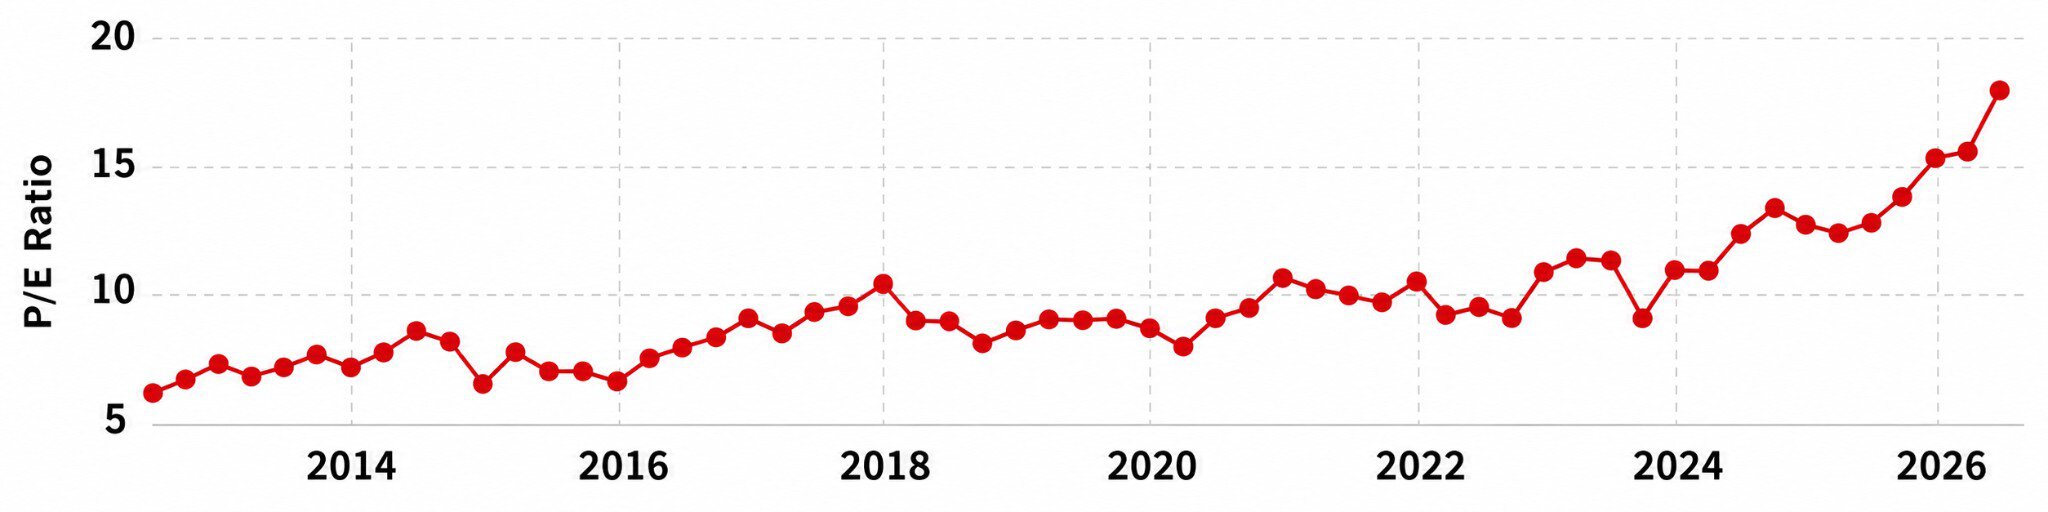
Paying that high a premium for the future stream of earnings doesn’t exactly scream “BUY NOW” to me (and there are many even more egregious examples of stretched valuations out there). Again, worth emphasizing that I think RBC is a great company, it’s simply a matter of paying a really high price for shares right relative to historical averages.
Earnings Per Share vs Dividend Growth in 2026
Because I’m looking to invest in Canadian dividend stocks for the next several decades, I like to look at medium and long-term trends when it comes to the company’s earnings and their dividend growth. These metrics tell me two important facts:
1) Is the company generally making more money each year?
2) Does management believe in rewarding shareholders with dividend increases on a consistent basis?
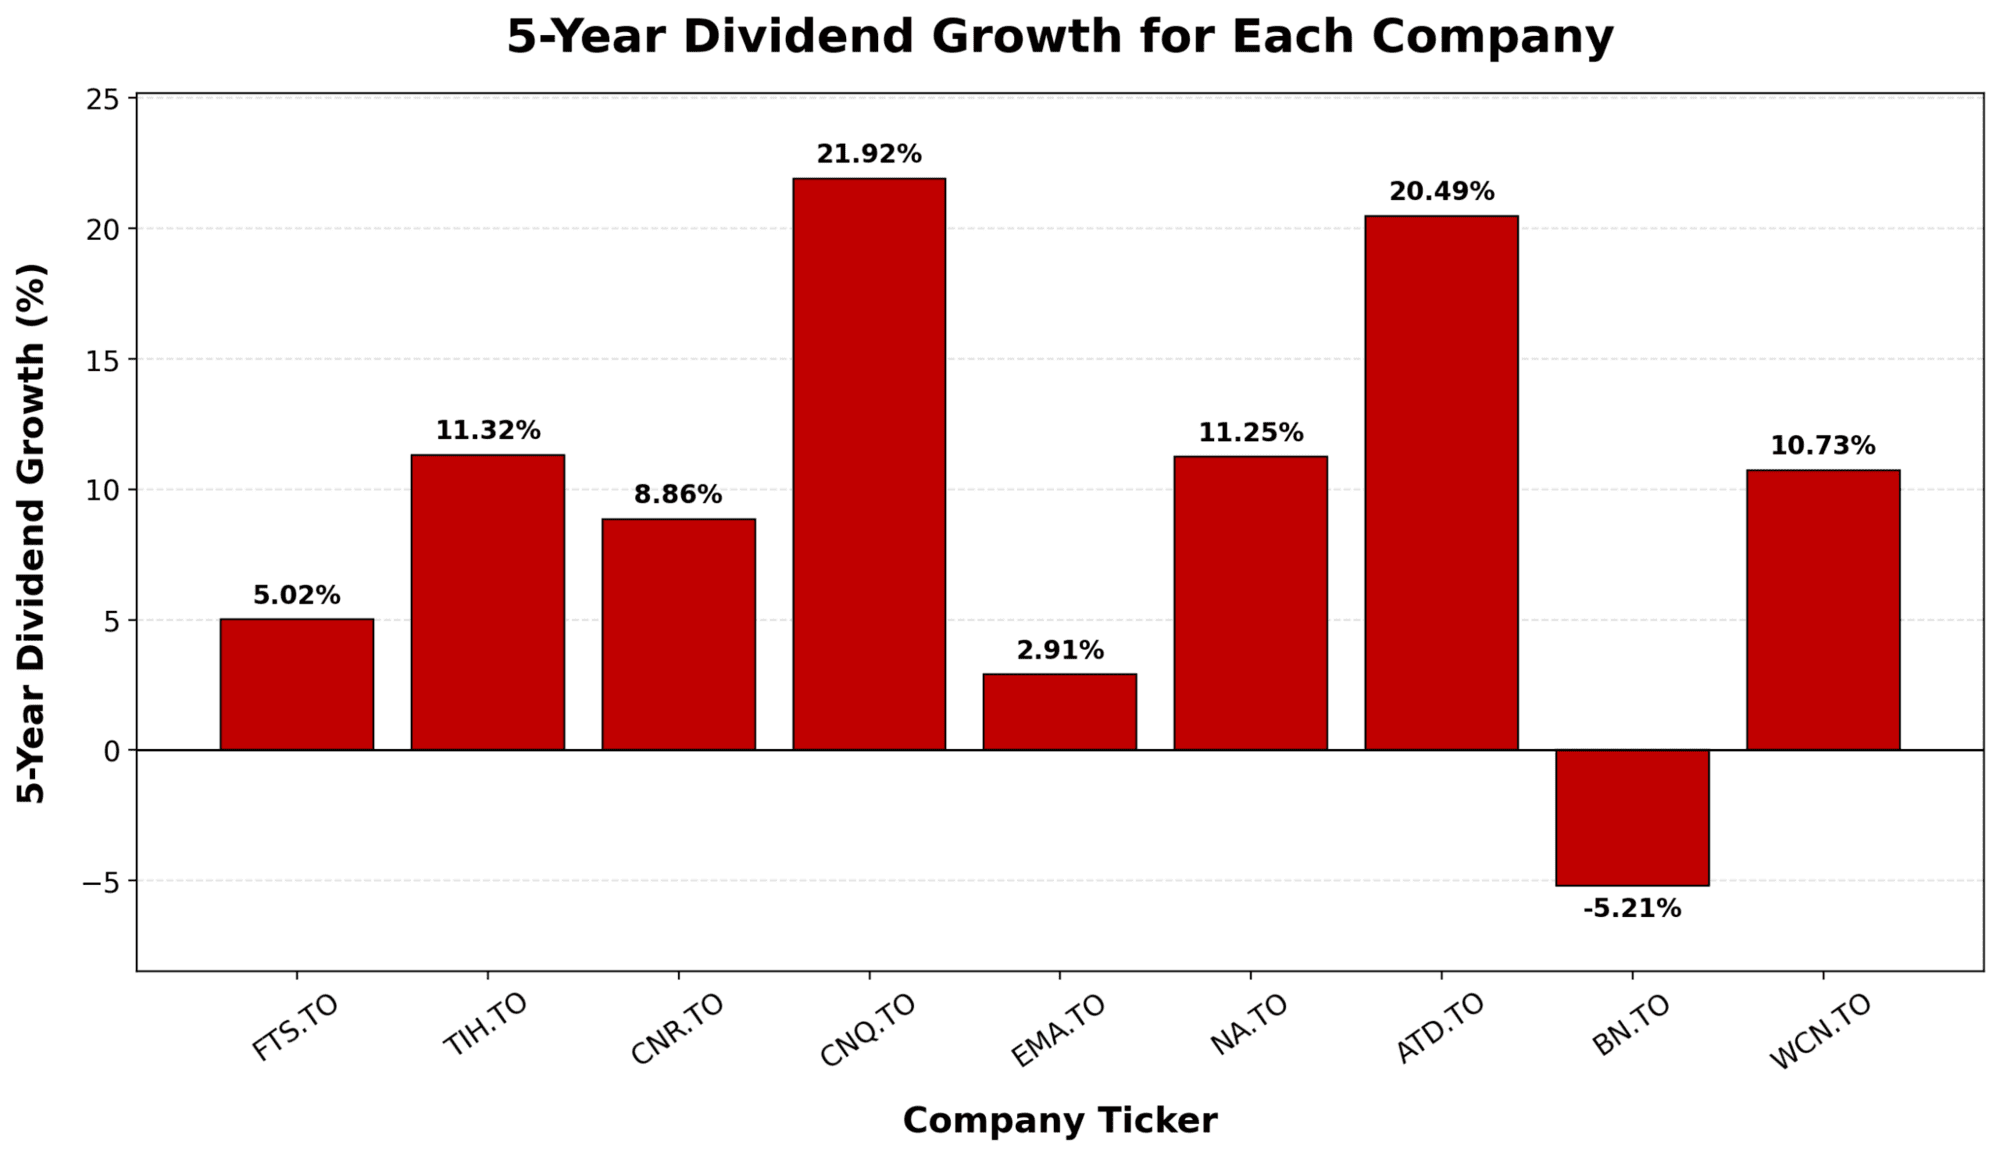
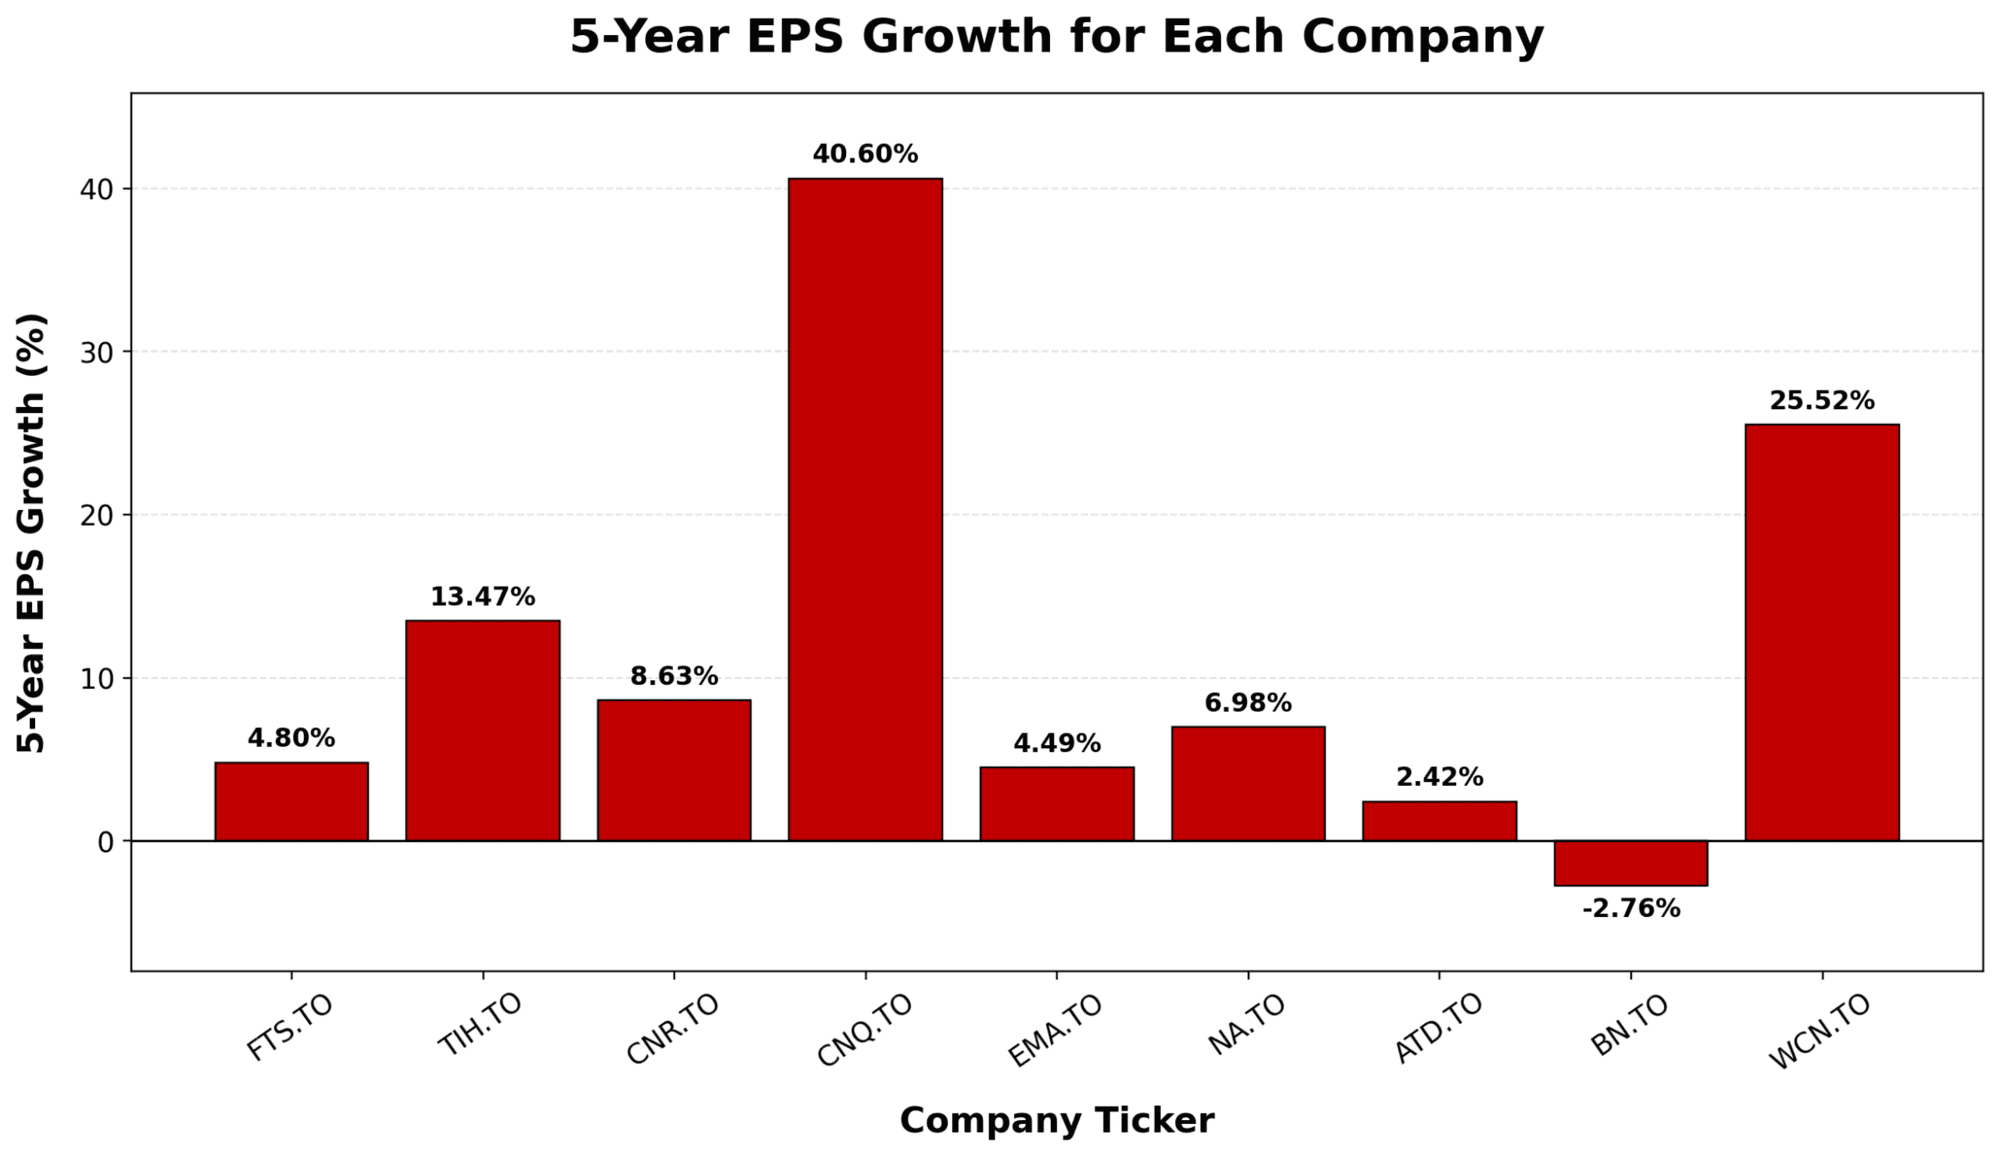
Here’s a look at how our top Canadian dividend stocks stack up over these two metrics (click each image to view in full size).
Now of course, 5-yr dividend growth and 5-yr earnings growth are not the only criteria that matters. It has to be taken in context.
For example, when we look at the two charts above, the following facts jump out at me:
- Brookfield (BN) looks like a real laggard. But keep in mind, the 5-yr total return is still over 60%. Alternative asset management is going to continue to grow, and continue to be a boon for Brookfield. I mean… when the current Prime Minister (and toast of the “Davos Elite”) used to run your company only a couple of years ago, then you’re probably doing ok.
- CNQ continues to look better and better. Canadian energy stocks remain a logical diversification play for countries looking to improve energy security, while CNQ’s low-cost production and long-life assets give it considerable resilience across commodity cycles.
- ATD is still a bit of a fascinating case. Earnings growth over the last five years was only 2.42%, but dividend growth came in at 20.49%. That’s due to the fact that ATD pays a very conservative dividend to begin with – but investors should always ask whether that pace can continue if earnings don’t accelerate.
- Fortis and Emera both look exactly like what you’d expect from utilities. Boring in a good way, with modest earnings growth and modest dividend growth that broadly line up.
- Who knew there was so much money in waste removal? If you’re looking for a recession-resistant stock, this one is probably it. But of course, it doesn’t come cheap as the P/E ratio is up around 37x.
*Free signup with access to stock tips & webinars + 60 days money back guarantee on the pro version.
My Top Canadian Dividend Stock Recommendations
Sorted in order of dividend streak:
Fortis (FTS.TO) – 52 Years of Dividend Growth
- 3.40% Dividend Yield
- 5.33% 5 EPS Growth
- 6.04% 5 Year Revenue Growth
- 4.65% 5 Year Dividend Growth
- 73.86% Payout Ratio
- 22.14 P/E
Investment Thesis:
Fortis has continued to do exactly what regulated utilities are supposed to do – steadily grow its rate base, invest in essential infrastructure, and convert that spending into predictable cash flow. As of its most recent filings, Fortis expects its regulated rate base to grow at roughly 6% annually through 2028, driven primarily by transmission and distribution investments rather than higher-risk generation projects.
The company is currently executing a $25 billion capital plan covering 2024 through 2028, an increase from its prior plan as grid hardening, reliability upgrades, and customer growth continue to demand capital. About 99% of Fortis’ assets are regulated, and roughly two-thirds of earnings now come from U.S. utilities, providing geographic and regulatory diversification that Canadian-only peers simply don’t have.
Financing remains conservative. Management expects approximately 55–60% of capital spending to be funded through cash from operations, with the remainder split between modest equity issuance and debt. Importantly, Fortis has avoided levering up aggressively at a time when higher interest rates are punishing capital-intensive businesses. Its credit metrics remain solid, with a BBB+ / A- range credit profile depending on the rating agency.
Renewables are not the headline story here, but Fortis continues to gradually increase exposure to cleaner energy and transmission assets tied to electrification. Clean energy and related infrastructure still represent a single-digit percentage of total assets, and management has been clear that returns and regulatory clarity come before optics. This measured approach has helped Fortis avoid the earnings volatility seen at more aggressive utility peers.
Dividend Growth Perspective:
Fortis remains one of the most reliable dividend growth companies in the Canadian market. The company has increased its dividend for 52 consecutive years, placing it in extremely rare territory even by global standards. Over the past five years, the dividend has grown at an average annual rate of approximately 6%, fully in line with management’s long-standing guidance.
Looking forward, Fortis continues to target 4–6% annual dividend growth, supported by expected earnings per share growth of roughly 6% per year driven by regulated rate-base expansion. The payout ratio remains reasonable for a utility, sitting in the 70–75% range, which provides enough room to fund growth while maintaining dividend stability.
*Free signup with access to stock tips & webinars + 60 days money back guarantee on the pro version.
Toromont Industries (TIH.TO) – 36 Years of Dividend Growth
- 1.11% Dividend Yield
- 10.45% 5 EPS Growth
- 7.24% 5 Year Revenue Growth
- 10.35% 5 Year Dividend Growth
- 34.05% Payout Ratio
- 32.46 P/E
Investment Thesis:
Toromont is one of those quietly excellent Canadian compounders that doesn’t always get grouped with “dividend stocks,” but behaves like one over full cycles. The business is built around two durable engines: the Equipment Group, which operates one of the largest Caterpillar dealership networks in North America, and CIMCO, its industrial and recreational refrigeration business.
The Equipment Group drives the bulk of revenue from construction and mining activity. Rentals, parts, and product support tend to be steadier and higher-margin parts of the business, and they provide a cushion when construction or commodity markets cool. That recurring service component is a big reason Toromont has been able to navigate cycles better than a pure equipment seller.
CIMCO adds a second layer of stability. Industrial refrigeration, cold storage, and recreational ice systems don’t move in lockstep with mining or construction, which helps smooth results over time.
Toromont has also been deliberate with acquisitions. Its long-standing Caterpillar dealership expansion laid the foundation, and more recent moves have added exposure to power systems manufacturing and data-centre-related infrastructure through AVL Manufacturing.
AVL has been ramping production, expanding capacity in the U.S., and broadening Toromont’s footprint beyond its traditional markets. Importantly, these acquisitions have been bolt-ons rather than empire-building deals.
Dividend Growth Perspective:
Toromont is a dividend growth stock, not a high-yield income stock.
What matters for dividend growth investors is sustainability. Toromont does not have to stretch its balance sheet to support the dividend, and management has consistently returned capital to shareholders while still reinvesting heavily in the business. Dividend growth tends to track long-term earnings growth rather than short-term swings in equipment sales.
Like any industrial stock, Toromont is not immune to economic cycles. A slowdown in mining or construction will impact results. That said, the combination of rentals, parts, service, and refrigeration work helps keep cash flow resilient enough to support ongoing dividend increases through most environments.
Canadian National Railway (CNR.TO) – 29 Years of Dividend Increases
- 2.18% Dividend Yield
- 3.10% 5 EPS Growth
- 4.31% 5 Year Revenue Growth
- 8.30% 5 Year Dividend Growth
- 46.78% Payout Ratio
- 21.53 P/E
Investment Thesis:
Canadian National Railway has long been considered best-in-class when it comes to operating efficiency, and while peers have narrowed the gap over the past decade, CNR still sits near the top of the industry. In recent years, its operating ratio has generally hovered in the low-60% range, even as inflation and labour costs have pressured margins across the sector.
CNR owns one of the highest-quality rail networks in North America, with a unique footprint connecting the Atlantic, Pacific, and Gulf of Mexico. That network is virtually impossible to replicate today, creating an enormous economic moat (alongside its main competitor, Canadian Pacific Kansas City). Rail remains the lowest-cost and most fuel-efficient way to move bulk commodities and heavy freight over long distances, which supports long-term volume demand and pricing power, even if growth comes in cycles.
From a cash flow perspective, CNR continues to convert a large portion of its revenue into free cash flow. Annual revenues have generally remained in the $16–18 billion range in recent years, with operating cash flow consistently exceeding $6 billion. That level of cash generation gives management flexibility to reinvest in the network, raise dividends, and buy back shares.
Dividend Growth Perspective:
Railroads are capital-intensive businesses, and CNR is no exception. Maintaining and expanding a continent-scale rail network requires billions in ongoing capital spending each year. CNR typically invests around $3-4 billion annually in maintenance and growth projects, which is necessary to preserve service reliability and long-term competitiveness.
Despite that heavy reinvestment burden, CNR continues to generate ample cash to support dividend growth. The company has increased its dividend for 29 consecutive years, and over the past decade the dividend has grown at a double-digit annualized rate. More recently, dividend growth has moderated into the high single-digit range, which is more sustainable given the company’s size and maturity.
The payout ratio remains conservative by dividend stock standards, generally sitting in the 35–40% range of earnings. That low payout provides a meaningful buffer during freight slowdowns and allows management to prioritize network investment without putting the dividend at risk.
Canadian National Resources (CNQ.TO) – 26 Years of Dividend Increases
- 3.56% Dividend Yield
- 17.78% 5 EPS Growth
- 11.55% 5 Year Revenue Growth
- 21.46% 5 Year Dividend Growth
- 45.38% Payout Ratio
- 12.49 P/E
Investment Thesis:
Canadian Natural Resources remains one of the highest-quality oil and gas producers in Canada, but the investment case looks different today than it did during the post-2020 rebound. With West Texas Intermediate generally trading in the $65–75 US range over the past couple of years, CNQ has proven it can generate strong cash flow without needing a commodity price boom.
The company’s biggest strength continues to be its cost structure. After years of heavy capital investment, CNQ has driven its corporate breakeven oil price down to roughly the mid-$30s. That margin of safety allows CNQ to remain profitable and free-cash-flow positive even during weaker oil markets.
Production is highly diversified across the oil sands, conventional heavy oil, light crude, and natural gas, which helps smooth results across cycles. Total production now exceeds 1.3 million barrels of oil equivalent per day, giving CNQ massive operating leverage when prices rise, but also scale advantages when they fall. Capital spending has normalized after years of aggressive growth.
Environmental and long-term demand concerns haven’t gone away. Oil sands assets are capital intensive and carbon heavy, and global energy policy continues to tilt toward electrification and renewables. That said, CNQ’s assets have extremely long reserve lives and low decline rates, making them well suited to a world where oil demand plateaus rather than collapses. As long as oil remains a necessary input to the global economy, low-cost producers like CNQ are likely to be the last ones standing.
CNQ’s share price has already reflected much of the post-pandemic recovery, more than doubling from 2020 lows. From here, returns are likely to be driven less by valuation expansion and more by disciplined operations and cash returns to shareholders.
Dividend Growth Perspective:
Canadian Natural Resources has quietly built one of the strongest dividend track records in the Canadian energy sector. The company has increased its dividend for 26 years, including through oil downturns that forced many peers to cut or suspend payouts.
The step-change came after 2021, when CNQ aggressively increased its base dividend while also layering on variable returns through share buybacks and special dividends. The dividend was increased by double-digit percentages in both 2022 and 2023, reflecting management’s confidence in the durability of cash flows at mid-cycle oil prices.
Today, the base dividend is deliberately set at a conservative level, with a payout ratio that typically sits well below 50% of free cash flow at $65–70 WTI. Excess cash is prioritized toward balance sheet strength and opportunistic buybacks, which gives CNQ flexibility if oil prices soften.
This approach makes CNQ less of a “pure income” stock and more of a total return dividend grower. Dividend growth will ebb and flow with the commodity cycle, but the underlying business has demonstrated it can support and grow payouts without relying on heroic oil price assumptions.
Emera (EMA.TO) – 17 Years of Dividend Increases
- 4.28% Dividend Yield
- 11.77% 5 EPS Growth
- 10.46% 5 Year Revenue Growth
- 2.62% 5 Year Dividend Growth
- 85.60% Payout Ratio
- 21.59 P/E
Investment Thesis:
Emera remains a diversified regulated utility with a solid footprint on both sides of the border. That translates into steady cash flows over the long term. Its core operations are anchored in Nova Scotia and Florida, with additional regulated utilities across several Caribbean jurisdictions.
Florida continues to be the centre of gravity for Emera’s growth. Tampa Electric now accounts for the majority of earnings. Florida’s population growth, rising electricity demand, and generally constructive regulatory environment have made it one of the more attractive utility markets in North America. You factor in new data centre electricity needs and you have yourself an excellent recipe for relatively safe returns.
Emera is in the middle of a large capital investment cycle focused on grid modernization, reliability, and cleaner generation. Over the 2024–2028 period, management expects to invest roughly $8–10 billion, with approximately two-thirds of that spending directed to Florida. These investments are heavily weighted toward regulated transmission and distribution assets rather than merchant power, which keeps risk contained.
Emera’s balance sheet remains the main point to watch. The company carries higher leverage than some Canadian utility peers following years of capital spending and acquisitions. Management has acknowledged this and has been prioritizing balance sheet stability as capital spending moderates. As interest rates remain higher than the pre-2022 era, disciplined financing will be key to protecting shareholder returns.
Dividend Growth Perspective:
Emera has increased its dividend for nearly two decades, maintaining a steady record of income growth through multiple economic cycles. Dividend growth has slowed in recent years, reflecting the company’s focus on funding capital projects and managing leverage, but the commitment to annual increases remains intact.
Management continues to guide toward 4-5% annual dividend growth. The payout ratio target remains in the 70–75% range of adjusted earnings, which is typical for a mature regulated utility but leaves less margin for error than lower-payout peers.
At recent prices, Emera’s dividend yield has generally sat in the 4-5% range. That yield reflects both the company’s stable cash flows and some lingering investor caution around debt levels and capital intensity.
*Free signup with access to stock tips & webinars + 60 days money back guarantee on the pro version.
National Bank (NA.TO) – 16 Years of Dividend Growth
- 2.51% Dividend Yield
- 8.02% 5 EPS Growth
- 12.28% 5 Year Revenue Growth
- 11.89% 5 Year Dividend Growth
- 45.77% Payout Ratio
- 17.62 P/E
Investment Thesis:
My personal Canadian dividend stock pick in 2021, 2022, and 2023!
National Bank has established itself as one of the two strongest performers among Canadian banks over the past decade, and the reasons for that outperformance remain largely intact. Rather than trying to outgrow the Big Six through sheer volume, NA has focused on higher-return business lines such as capital markets, wealth management, and private banking.
Private Banking 1859 has grown into a meaningful contributor to earnings, particularly among high-net-worth and entrepreneurial clients. National Bank has also expanded its private banking presence outside Quebec, including targeted growth in Western Canada, which has helped diversify its revenue base without diluting its core strengths.
While the bank remains heavily concentrated in Quebec, that exposure has historically been a feature rather than a flaw. Quebec has provided a stable deposit base and strong client relationships, while National Bank has supplemented that regional focus through partnerships and credit exposure tied to Power Corporation-affiliated investment and insurance businesses. That said, given the talk of Quebec referendums rearing its ugly head, I’m increasingly worried about the tail risk here.
National Bank has also shown a willingness to pursue non-traditional growth vectors. Its majority stake in ABA Bank has turned Cambodia into a surprisingly meaningful earnings contributor, now accounting for roughly 15% of net income in stronger years. Unlike some international expansions by Canadian banks, ABA has delivered consistent profitability.
Dividend Growth Perspective:
Like all banks, National Bank is exposed to economic cycles. Rising unemployment, slower credit growth, or a prolonged market downturn can pressure earnings. Capital markets revenue, in particular, remains volatile and can swing meaningfully from quarter to quarter if equity issuance, M&A activity, or trading volumes dry up. Given the outsized impacts of tariffs on Quebec, National Bank is a bit exposed there as well.
That said, National Bank’s balance sheet looks quite solid. Its capital ratios remain comfortably above regulatory minimums, and its dividend payout ratio has generally stayed in the 40–50% range of earnings. This provides room to absorb earnings volatility without putting the dividend at risk.
National Bank has increased its dividend every year for more than a decade, and its combination of revenue growth, earnings growth, and dividend growth continues to form one of the strongest dividend triangles in the Canadian banking sector.
Alimentation Couche-Tard (ATD.TO) – 16 Years of Dividend Growth
- 1.08% Dividend Yield
- 7.26% 5 EPS Growth
- 8.74% 5 Year Revenue Growth
- 19.14% 5 Year Dividend Growth
- 17.60% Payout Ratio
- 16.79 P/E
Investment Thesis:
Alimentation Couche-Tard has built a dominant position in the global convenience store industry by sticking to a simple but hard-to-execute playbook: buy smart (don’t overpay), integrate quickly, and relentlessly improve operation margins. That formula has driven steady revenue and earnings growth for more than a decade and continues to underpin the long-term investment case today.
Couche-Tard now operates over 17,000 stores worldwide, primarily under the Circle K banner, with a strong footprint across North America and Europe and a growing presence in select international markets. The business generates revenue from a mix of fuel sales, in-store merchandise, and food service. Fuel remains a major traffic driver and profit contributor, but management has spent years deliberately reducing reliance on any single category.
Organic growth has become increasingly important. Initiatives such as Fresh Food Fast, improved pricing and promotions, expanded private-label assortments, and tighter cost controls have helped lift margins and same-store performance. At the same time, Couche-Tard has been investing in digital tools and loyalty programs to better target promotions and optimize merchandising, quietly improving profitability across its store base.
Longer term, management has laid out an ambitious but credible roadmap through its “10 for the Win” strategy, which targets more than $10 billion in EBITDA by 2028. Acquisitions remain the company’s biggest differentiator. Couche-Tard’s ability to integrate acquired stores, extract synergies, and improve returns has consistently set it apart from peers.
While its high-profile failed pursuit 7-Eleven grabbed headlines in late 2024, history suggests investors shouldn’t fixate on any one deal. Management has repeatedly shown discipline at the negotiating table, walking away when valuations don’t make sense and pivoting back to smaller, high-return acquisitions when necessary.
Concerns around electric vehicles and declining cigarette sales are real, but they are not new. Couche-Tard has been planning for these shifts for years by expanding fresh food offerings, experimenting with new store formats, and rolling out EV charging infrastructure across select locations. Fuel demand isn’t disappearing overnight, and Couche-Tard’s scale and adaptability position it well to manage a gradual transition rather than be blindsided by it.
Dividend Growth Perspective:
Couche-Tard is a textbook example of a dividend growth stock that prioritizes compounding over yield. The dividend has grown at a double-digit rate over long periods, supported by steady earnings growth and an extremely conservative payout ratio.
That payout ratio typically sits below 25% of earnings, giving management significant flexibility. Cash flow is first allocated to reinvestment and acquisitions, with dividends rising as a byproduct of a growing business rather than as a constraint on it. This approach has allowed Couche-Tard to increase dividends aggressively without stretching the balance sheet or sacrificing growth opportunities.
For income-focused investors, Couche-Tard requires patience. The current yield is modest, but the combination of strong free cash flow generation, disciplined capital allocation, and consistent execution has historically delivered excellent total returns.
As long as management continues to follow its proven playbook, Couche-Tard remains one of the strongest long-term dividend growth stories in the Canadian market.
Brookfield Corp (BN.TO) – 16 Years of Dividend Growth
- 0.74% Dividend Yield
- -18.53% 5 EPS Growth
- 1.64% 5 Year Revenue Growth
- -5.22% 5 Year Dividend Growth
- 48.42% Payout Ratio
- 74.40 P/E
Investment Thesis:
I’ve been a bit tentative when it comes to the Brookfield family of companies, as it can be quite difficult to really dig into their quarterly statements due to their size and complexity. That said, their past results and unique corporate structure have ensured access to billions of dollars in liquidity to finance its projects.
Unlike Brookfield Asset Management, which operates as a largely asset-light fee manager, BN is asset-heavy by design. It not only earns fees on assets under management, but also deploys its own capital alongside clients, allowing it to participate directly in capital appreciation and long-term value creation.
That dual role is central to Brookfield’s strategy. BN invests across real estate, infrastructure, private equity, renewables, and private credit. The company has access to billions of dollars in liquidity through permanent capital, long-duration funds, and institutional relationships, which allows it to act decisively during periods of market stress when capital is scarce.
Asset recycling is a core part of the playbook. Brookfield routinely sells mature assets at attractive valuations and redeploys that capital into distressed or undervalued opportunities. In simple terms, it tries to buy when others can’t, improve assets operationally, and sell when demand returns. That cycle has been repeated across multiple market downturns and is a major driver of long-term compounding.
Brookfield is also positioned to benefit from a structural shift in global investing. Management estimates that alternative assets could grow from roughly 25% of global asset allocations today to as much as 60% by 2030. Whether or not that exact number is reached, institutional investors continue to increase exposure to infrastructure, private credit, and real assets – areas where Brookfield has decades of experience and scale.
Dividend Growth Perspective:
Brookfield Corporation is not an income stock. Following the restructuring and separation of Brookfield Asset Management, BN’s dividend yield has remained low, generally under 1%, and is not the primary reason to own the shares.
Management has signalled an intention to grow the dividend over time, supported by fee-related earnings, asset monetization, and balance sheet strength. However, dividend growth is secondary to capital deployment and long-term value creation.
Investors looking for higher current income may prefer Brookfield Asset Management, which earns recurring fees on assets under management. Brookfield Corporation, by contrast, offers a blend of fee income, asset ownership, and capital appreciation. BN is best viewed as a long-term compounder with a growing dividend rather than a traditional high-yield Canadian dividend stock.
So why include BN on a list of our best Canadian dividend stocks? Because I’m ultimately looking for companies that can compound shareholder wealth over a long period of time, not simply maximize income today.
Brookfield’s recent restructuring makes its five-year dividend numbers particularly messy, but the underlying investment case remains. The tiny current yield means BN won’t appeal to income-focused investors, but I think it still belongs in a dividend growth portfolio with a long enough time horizon.
*Free signup with access to stock tips & webinars + 60 days money back guarantee on the pro version.
Waste Connections – 15 Years Of Dividends Growth
- 0.89% Dividend Yield
- 13.25% 5 EPS Growth
- 10.51% 5 Year Revenue Growth
- 10.28% 5 Year Dividend Growth
- 31.01% Payout Ratio
- 38.49 P/E
Investment Thesis:
Waste Connections is one of the best examples of a “boring business” that can still deliver not-so-boring shareholder returns. Garbage pickup is about as recession-resistant as it gets. Municipalities and businesses don’t really have the option to pause service when the economy slows.
The company’s edge comes from vertical integration and market selection. As of the most recent full-year reporting, it operated roughly 113 landfills, 222 transfer stations, and 89 recycling facilities. Owning scarce, permitted disposal capacity matters because it gives the company leverage in pricing, routing, and long-term planning. It also makes it brutally difficult for competitors to replicate the business in any meaningful way (good luck permitting a new landfill in 2026).
Management has also built the business around secondary and rural markets rather than fighting constant price wars in the most competitive urban cores. The company’s mix includes a meaningful base of exclusive or franchise-style markets, with the remainder largely in competitive markets where it tends to have high market share.
Financially, the model has continued to do what you want it to do. In 2024, Waste Connections generated about $8.9 billion in revenue and roughly $2.9 billion in adjusted EBITDA, with an adjusted EBITDA margin around 32.5%. For 2025, we saw $9.45 billion and adjusted EBITDA around $3.12 billion, showing margin improvement toward 33%.
That’s a pretty clear signal that pricing and operating discipline are still doing their job, even as costs move around. Adjusted free cash flow has been running in the $1.2 to $1.3 billion range, which is the real fuel that powers acquisitions and shareholder returns.
Acquisitions remain a big part of the compounding story. Waste Connections has a long track record of buying smaller operators, integrating routes, improving pricing, and raising margins over time. Over the last five years, it has completed more than 100 acquisitions totaling roughly $2.2 billion in annualized revenue. That’s not “one big bet” M&A. That’s a steady roll-up machine.
Waste Connections is a cash flow business with pricing power, high barriers to entry, and a disciplined acquisition engine. It’s not flashy. It just tends to keep compounding.
Dividend Growth Perspective:
Waste Connections is another stock that isn’t going to pop up on a lot of dividend lists due to its relatively low yield – but it’s an excellent dividend growth story. The yield typically sits under 1% because the stock has compounded so well (not because the dividend is neglected).
Management has been raising the dividend at a double-digit clip for years, and in October 2025 the company increased its quarterly dividend by 11.1% to US$0.35 per share (up from US$0.315). That brings the annualized dividend to about US$1.40 per share.
This is the kind of company that will usually prioritize reinvestment and acquisitions first (because the returns can be excellent), then steadily grow the dividend alongside earnings and cash flow. If you’re building a dividend growth portfolio and you want exposure to a defensive, infrastructure-like business with real pricing power, WCN fits beautifully.
My Recent Dividend Track Record
I started making public dividend stock picks beginning in 2021. That year, I predicted that Canada’s midstream companies were getting way too much bad press and that their value was being driven down by the underlying price of commodities like oil and natural gas.
We thought there was a market inefficiency there as the pipelines only have a loose relationship between commodity prices and their profit margin. Our top Canadian dividend stock pick was Enbridge, and it has paid off quite well. We sold about 10% before the stock hit the top and haven’t added to our position since. It has consistently paid out an excellent dividend ever since.
More recently, my Canadian dividend kings pick for 2022, 2023, and 2024 was National Bank, and I’ve been very happy with its overall performance. So, while my Sun Life stock pick didn’t measure up in 2025, I’d say I’ve steered more folks right than wrong over the years.
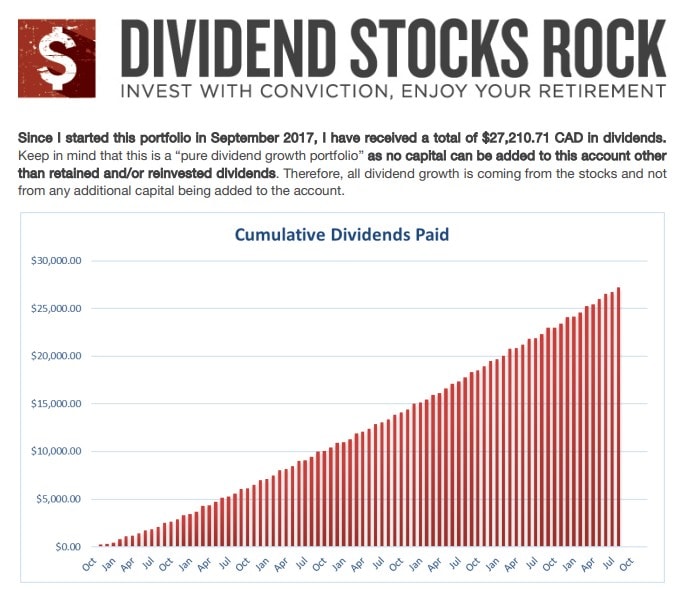
I’m stacking up well against the benchmarks, and I’m even beating my dividend buddy Mike Heroux for a couple of his portfolios. Here’s a cool look at Mike’s public dividend stock portfolio since he started the DSR service back in 2017 (and made his picks 100% public knowledge the entire way).
Why Telecom Stocks Like Telus or Bell Didn’t Make The Cut
Let’s be honest: If you had told a Canadian investor in 2016 that the Big Three telecoms would be in this position a decade later, they probably would have laughed.
Bell, Rogers, and Telus appeared to have one of the safest business models in Canada. Recurring monthly revenue, enormous barriers to entry, limited competition, and customers who were becoming more dependent on their services each year.
Canadians did not stop using their phones or home internet. The telecom companies simply ran head-first into a brutal combination of too much debt, years of heavy capital spending, higher interest costs, slower population growth, regulatory uncertainty, and an increasingly aggressive price war.
That combination exposed how fragile the old “telecom dividend equals bond substitute” argument really was.
In May 2025, BCE reduced its annual dividend from just under $4 per share to $1.75. The cut of roughly 56% gave Bell more room to pay down debt and invest in the business, but it was still a painful reset for shareholders who had treated the dividend as untouchable.
I had been uncomfortable with Bell’s payout ratio and balance sheet for years, which is why it had not appeared on my top dividend stock lists since 2020.
Then, on July 31, 2026, Telus followed over the dividend cliff. It reduced its quarterly dividend from $0.4184 per share to $0.1875. That takes the annual payout from $1.6736 to $0.75 (a reduction of approximately 55%).
The company also abandoned its dividend-growth framework, eliminated the discount attached to its dividend reinvestment plan, and lowered its targeted payout ratio to between 45% and 60% of trailing 12-month free cash flow. At the same time, projected capital spending increased from approximately $2.3 billion to $2.6 billion.
While the underlying telecom operations held up considerably better, products like Telus Digital, Telus Health really dragged it down. Second-quarter free cash flow actually increased slightly to $545 million, mobile network revenue grew 1%, and the core Canadian telecom business remained relatively stable.
I still believe Telus owns some excellent assets, and the dividend cut probably improves its long-term chances of recovering. Investors buying today are betting that new management can reduce debt, control spending, stabilize Telus Digital, protect the economics of the core telecom business, and deliver the promised free cash flow growth.
Rogers is now the odd one out in the Canadian telecom dividend discussion.
Its quarterly dividend has remained at $0.50 per share since 2019. That means dividend investors have received no growth for years, but Rogers also avoided making promises that its cash flow could not support.
The company has instead focused on integrating Shaw, reducing leverage, limiting capital spending, and extracting more cash from its various assets. Rogers still carries substantial debt, faces pricing pressure, and operates in the same uncertain regulatory environment. That said, it definitely has the least dramatic dividend story of the three.
Name | Ticker | Price | Dividend Yield | Payout Ratio | P/E | Market Cap |
Telus | T.TO | 13.53 | 5.45% | 227.49% | 22.93 | 21.66B |
BCE Inc. | BCE.TO | 31.67 | 5.49% | 32.13% | 4.27 | 29.73B |
Rogers | RCI.B.TO | 48.01 | 4.12% | 15.65% | 4.26 | 26.26B |
Canadian Stocks With 10+ Year Dividend Growth
The last several years have put Canadian dividend stocks through an unusually wide range of challenges: a pandemic-driven crash, rapidly rising inflation and interest rates, commodity volatility, and shifting economic growth expectations.
Throughout all of this, there are 38 companies in Canada that have just boringly raised their dividends year after year. Click below for the list of Canadian dividend growth stocks that weren’t shaken by the pandemic, bubbles, panic, inflation, or interest rates.
Canada’s 38 Dividend Growth Stocks
(Ten Years or More Dividend Increases)
Click below to find all the new additions to the previous top Canadian stocks. The following have been handpicked for their ability to face the economic lockdown and thrive going forward.
Dividend Stocks vs Dogs of the TSX
Our list of the best Canadian dividend stocks and the Dogs of the TSX are built using very different approaches.
Our dividend growth stock picks focus on long-term quality, including dividend growth, earnings and revenue growth, payout sustainability, and valuation. A high dividend yield alone isn’t enough to make our list.
The Dogs of the TSX, also known as Beating the TSX (BTSX), is a more mechanical value strategy. It starts with the highest-yielding stocks in the TSX 60 and uses a set of rules to identify potentially undervalued dividend stocks.
There can be some overlap between the two lists, but a stock can qualify for one and not the other. To provide just one quick example, a falling share price can push a company’s yield high enough to attract the Dogs strategy even if it doesn’t meet the criteria for our picks on this page.
You can see the current picks and full methodology in our Dogs of the TSX guide.
Dividend Investing in Canada – Frequently Asked Questions
Final Thoughts on the Best Canadian Dividend Stocks
here’s no single metric that identifies the best Canadian dividend stocks. A high yield can look attractive, but as Bell and Telus investors recently learned, that yield doesn’t mean much if the underlying business can’t comfortably support it.
That’s why I continue to favour companies with growing earnings, sustainable payout ratios, and a long history of increasing dividends. Fortis remains my top Canadian dividend stock for 2026, but the companies on this list offer different combinations of income, dividend growth, and long-term capital appreciation.
I’ll continue updating the numbers and my picks as earnings, valuations, and dividend announcements change throughout the year. If you have other picks or any questions, feel free to leave a comment below!
*Free signup with access to stock tips & webinars + 60 days money back guarantee on the pro version.

Can you comment on the argument that focusing on “dividend” stocks distracts from companies that do not pay dividends but are similarly successful conservative investments whose total growth is just as or more reliable than that of dividend growers? Are we limiting our universe to Canadian energy/utilities/finance for the most part, and missing out on other good opportunities? The argument is that if companies didn’t pay a dividend, their share price/value would increase by the amount of the dividends paid.
Hey Paul,
FT doesn’t really stop by the comment sections these days, but there is definitely some validity to that argument. For me, what it really boils down to is the idea of behaviour modification. A lot of people are just really really motivated by building up the dividend stream – and then staying the course NO MATTER WHAT. Focusing on that dividend usually results in less panic selling. That said, the math-based idea that reinvesting money into the company (to make a more valuable company) or buying back stocks with profits, is essentially just as good as paying out the dividend – is sound to me. There’s also some good tax-based reasons for dividends in a non-registered account.
FYI: In the first table the tickers for CNQ and CNR are reversed. Might want to update.
Thanks Dave!
ATD.TO when does a growth stock cease being one ?
How does an UNDER 1.5% dividend put Stella Jones anywhere CLOSE to being on your list of “Best Canadian Dividend Stocks”.
It’s not all about the dividend – but total return as well Michael.
It’s either a “Best Canadian DIVIDEND Stock” or it isn’t.
If I’m looking for a list of “Best Canadian Capital Gains Stocks”…….that’s what I’ll type into my search bar.
Thanks FT, Particularly enjoyed “Most recent news “
Any thoughts on what government policy towards transitioning from natural gas to electricity will do to companies like Fortis? (and to a lesser extent, pipelines and other oil utilities?) I’m wondering if they may no longer have as solid a future as once believed.
About 2 years ago, the City of Vancouver changed the building code to; no more heating of newly constructed homes by nat/gas. Apparently there is now a problem getting power turned on for occupancy due to BC hydro being overwhelmed. Allegedly, the City now has reversed their thoughts on no more nat gas for heating new homes!
Does Algonquin count as a eligable dividend for a non registered account? It pays its distributions in USD no? So is there the 15% withholding tax? Wondering about using it in a smith manoeuvre
No withholding tax. Buy it on the TSX and you’re good to go!
how does the pe ratio play ? what should we be looking at in a pe ratio
Thank you so much for the list ! what are your thoughts in regards to BCE and Telus payout ratio you think the dividends are safe even though they both are paying aprox 130% ?
New to this board. Just curious about the energy space further to Paul N and FT comments in Sept. I got burned in the downturn with energy (ie opportunity cost of holding a under-performing sector only to be hit by the coronavirus cyclical downturn that may last years). There is no question that the sector was cheap before the downturn, but thanks to the green folks, ESG investors, and the Canadian government, I am not sure that in the long term a proper multiple will ever return. I have no doubt that earnings and cash flow will return, as well as probably $100 oil due to chronic under investment, but it appears to me that these stocks – even SU and CNQ – are no longer buy and hold investments, but have become more like trades on the hopes of a large and quick spike in oil price. I am disappointed as I disagree with investors buying up cash-burning Tesla shares at huge multiples while selling Canadian energy stocks that were bringing in cash hand over fist, but seems to me that is unfortunately the way investing is going. Ultimately the sentiment could spread to TRP and ENB despite stable outlook (I still hold the pipelines though).